Cyprus holding structures for Kazakh groups
A Cyprus holding company established above Kazakh operating subsidiaries reduces withholding tax on dividends from 15% to 5% under the double tax treaty. Dividends received are exempt in Cyprus, gains on the disposal of a subsidiary are exempt, and no Cyprus withholding tax arises on distributions to shareholders.
How the holding company is positioned
A single Cyprus company holds the shares in the Kazakh operating subsidiaries. Profits are distributed upwards as dividends and may be distributed onwards to shareholders without further Cyprus tax.
Payments from Kazakhstan
The Convention between Cyprus and Kazakhstan entered into force on 17 January 2020 and applies to income arising from 1 January 2021.
| Payment from the Kazakh subsidiary | Domestic rate | Treaty rate |
|---|---|---|
| Dividends, where the recipient holds at least 10% of the capital | 15% | 5% |
| Interest on shareholder and third-party loans | 10% | 10% |
| Royalties | 15% | 10% |
| Payments to listed preferential-tax jurisdictions | 20% | Not available |
The reduced rate applies where the Cyprus company is the beneficial owner of the income and holds at least 10% of the capital of the payer directly. Hong Kong, the British Virgin Islands and the Cayman Islands are included on the Kazakh list of preferential-tax jurisdictions and are subject to a flat 20%, with no treaty relief available.
Position at the holding company
| At the Cyprus holding company | Position from 1 January 2026 |
|---|---|
| Dividends received from the subsidiary | Exempt |
| Gains on the disposal of the subsidiary | Exempt |
| Distributions to shareholders | No withholding tax |
| Interest paid to non-residents | No withholding tax |
| Royalties, where the intellectual property is not used in Cyprus | No withholding tax |
| Corporate income tax on trading and finance income | 15% |
| Qualifying intellectual property income | 3% effective |
| Carry-forward of tax losses | 7 years |
The participation exemption on dividends received is not subject to a minimum shareholding or holding period. It is restricted only where the paying company derives more than 50% of its income from investment activity and is subject to tax at an effective rate below 7.5%, which will not ordinarily apply to a Kazakh operating subsidiary.
Further uses of the structure
Groups commonly establish the structure for the treaty position and subsequently extend it to financing, intellectual property and exit planning.
Financing the subsidiaries
Equity introduced into the Cyprus company and on-lent to Kazakhstan attracts a notional interest deduction. The deduction is calculated by reference to the yield on the government bonds of the state in which the equity is employed, and Kazakhstan carries one of the higher reference rates available.
Intellectual property
Software, patents and trademarks held by the Cyprus company qualify for an effective rate of 3% on qualifying income under the IP Box. The regime applies the OECD modified nexus approach and has been reviewed and accepted by the OECD Forum on Harmful Tax Practices and the EU Code of Conduct Group.
Disposal of the business
Gains on the disposal of shares and other titles are exempt from Cyprus tax, without a minimum shareholding or holding period. The exemption does not extend to companies deriving their value principally from immovable property situated in Cyprus.
Distributions to shareholders
Cyprus imposes no withholding tax on dividends paid to non-residents, irrespective of jurisdiction or treaty position. Shareholders who become Cyprus tax resident and are non-domiciled are exempt from the defence contribution on dividends for 17 years.
Substance requirements
Treaty relief in Kazakhstan is conditional. Under the Tax Code in force from 1 January 2026 the Kazakh payer must establish that the recipient is the final recipient of the income, must hold a certificate of tax residence by 31 March of the following year, and, since April 2026, must satisfy its bank that outbound distributions have economic substance. A company that cannot demonstrate management and control in Cyprus will not meet these requirements.
Board composition
A majority of the directors should be Cyprus tax residents and should exercise genuine decision-making authority.
Board meetings
Meetings should be convened and held in Cyprus, and minuted in substance. Minutes recording the ratification of decisions taken elsewhere are a common point of failure on review.
Banking
Bank accounts should be maintained in Cyprus and operated by signatories resident in Cyprus.
Registered office and records
Registered office, statutory registers and accounting records maintained in Cyprus.
Statutory audit
All Cyprus companies are subject to statutory audit irrespective of size. No small-company exemption is available.
Kazakh documentation
The Kazakh payer requires an annual certificate of tax residence, together with evidence supporting beneficial ownership of the income.
Alternative holding jurisdictions
Withholding tax on a dividend from Kazakhstan, by jurisdiction of the holding company.
| Jurisdiction | Withholding tax on dividends | Principal consideration |
|---|---|---|
| Cyprus | 5% | EU member state with a double tax treaty in force. No withholding tax on distributions and no tax on the disposal of subsidiaries. |
| Netherlands | 5% | Treaty position comparable. Dividend withholding tax of 15% applies on distribution, and the substance requirements include a minimum Dutch wage cost of €100,000. |
| Singapore | 10% | The 5% treaty rate requires a 25% direct holding. Certificates of residence are not ordinarily issued to foreign-owned passive holding companies. |
| United Arab Emirates | 5% | Treaty in force. Free zone status is subject to seven conditions, and failure of any one results in taxation at 9% for five tax periods. |
| Hong Kong | 20% | No treaty. Listed by Kazakhstan as a preferential-tax jurisdiction. Outward redomiciliation is not available. |
| Cayman Islands | 20% | No treaty. Listed by Kazakhstan as a preferential-tax jurisdiction. |
| British Virgin Islands | 20% | No treaty. Listed by Kazakhstan, and included on the EU list of high-risk third countries since 9 January 2026, requiring enhanced due diligence by EU institutions. |
| AIFC, Astana | — | Remains within the Kazakh jurisdiction. No access to EU directives, and Kazakh currency control continues to apply to the structure. |
An existing holding company can in most cases be relocated. Companies incorporated in the British Virgin Islands or the Cayman Islands may be re-registered in Cyprus by way of continuation, retaining their legal identity. Dutch companies may convert or merge into a Cyprus company under the EU Mobility and Merger Directives. Hong Kong and Singapore do not permit outward redomiciliation, and a Cyprus company is interposed instead. The route available will depend on the jurisdiction and the circumstances of the company.
How we can help
Formation, accounting, statutory audit and tax advisory are delivered by a single team, under the responsibility of the Managing Director.
Review of the existing structure
We review the current ownership chart and the most recent financial statements, and set out the effective tax position of the existing structure against the position under a Cyprus holding company.
Formation
Incorporation, registered office, statutory registers and introduction to a Cyprus bank. Typically two to three weeks from receipt of the due diligence documentation.
Establishing substance
Appointment of resident directors, constitution of the board, and the operating arrangements required to demonstrate management and control in Cyprus.
Ongoing compliance
Bookkeeping, statutory audit, the corporate income tax return, the annual certificate of tax residence required by the Kazakh payer, and transfer pricing documentation where the thresholds are exceeded.
Technical briefings
Available in full, without registration.
Cyprus for Kazakh Groups
The treaty article by article, the notional interest deduction, intellectual property holding, repatriation, the exit, and the Kazakh controlled foreign company analysis.
Substance for Cyprus Companies
The scope of the substance requirement, the indicators examined by tax authorities in practice, core income-generating activities by company type, and the evidence file to be maintained.
The Cyprus IP Box Regime
Legal basis, the effect of the 2026 reform, qualifying assets and income, the modified nexus fraction, compliance obligations, disposals and amortisation.
Relocation to Cyprus
For shareholders relocating alongside the structure: immigration, residence permits, taxation, banking, real estate, healthcare and schooling.
Kazakhstan Legal Forum 2026
Rixos Almaty, 24 and 25 September 2026.
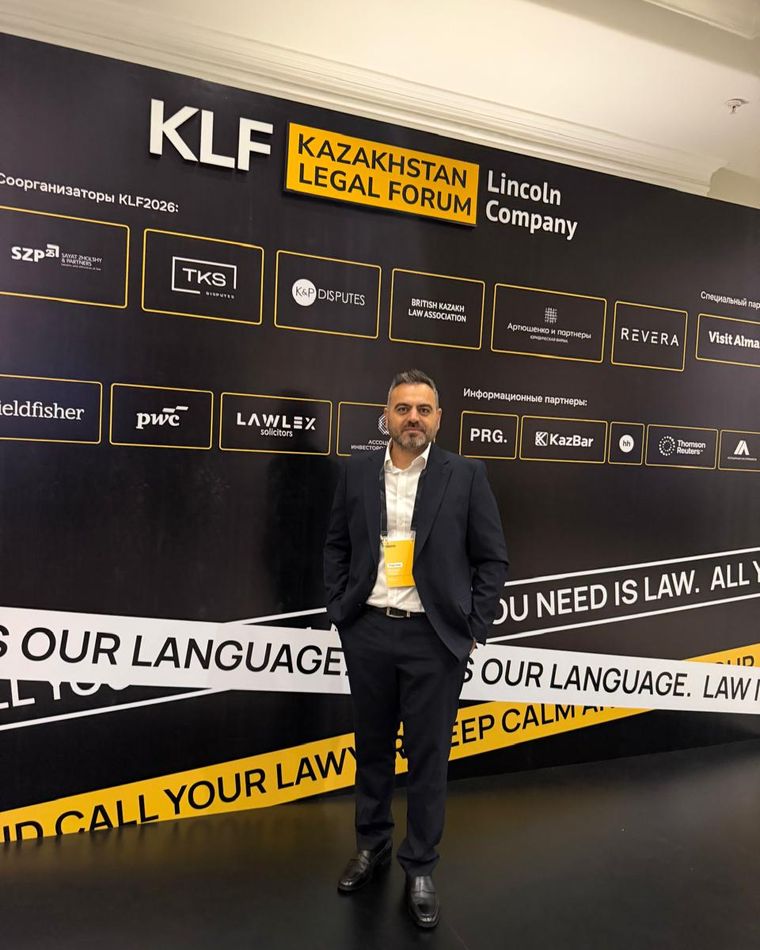
Nicolas Trikkis attended the sixteenth Kazakhstan Legal Forum at the Rixos Almaty on 24 and 25 September 2026, the principal annual gathering of in-house counsel, private practice lawyers and finance officers in Kazakhstan.
We are grateful to Lincoln Company and to the co-organisers for a forum of considerable quality, and for the hospitality extended to us throughout. Kazakh hospitality is not something adequately conveyed in writing. We were glad to experience it, and grateful to the colleagues who took the time between sessions to share something of Kazakh culture, language and history.
The panel sessions, and the private meetings that followed, were of real value. Hearing Kazakh counsel and in-house teams describe how the new Tax Code is being applied in practice — the beneficial ownership and final recipient tests, the discipline now required around certificates of tax residence, currency contract registration, and the manner in which banks are reviewing cross-border payments — is worth considerably more than desk research.
We returned with our view confirmed and better founded: Cyprus is a serious and increasingly well-matched jurisdiction for Kazakh groups structuring outward. The discussions begun in Almaty continue, and we look forward to returning.
CFA Auditors
Clients are advised by the Managing Director directly.
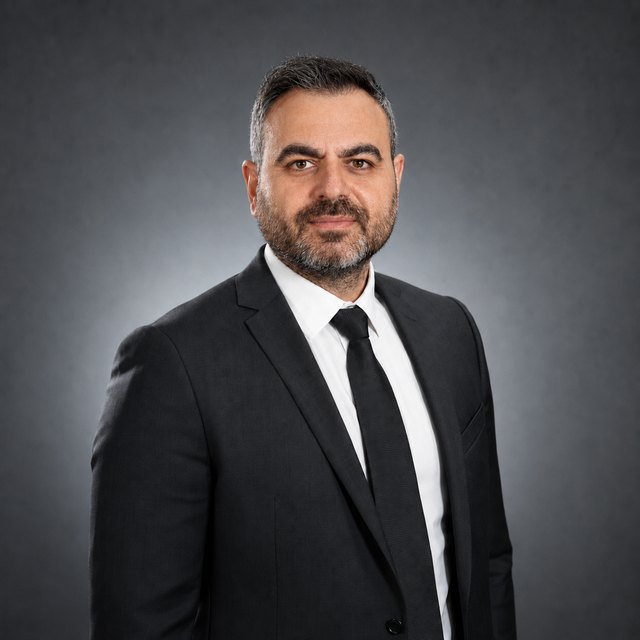
Nicolas Trikkis
Nicolas Trikkis holds overall responsibility for the firm’s engagements, from incorporation through to the continuing administration of established structures. He attended the Kazakhstan Legal Forum 2026 in Almaty in September 2026.
CFA Auditors has practised in Larnaca since 2010 and is regulated through ACCA and ICPAC membership. The firm’s principal sectors are real estate and construction, communications and technology, and financial services, which together account for the majority of Kazakh investment into Cyprus.
Request an initial review
An ownership chart and the most recent financial statements are sufficient for us to set out the current effective tax position, the position under a Cyprus holding structure, and the cost of establishing and maintaining it. There is no charge for the initial review.
Bybloserve Business Centre, 3rd Floor
6051 Larnaca, Cyprus